Getting a Jumbo Loan With a Low Down Payment and No Mortgage Insurance
Learn what lenders look for on jumbo loans, why requirements vary, and how some borrowers may qualify with a lower down payment and no PMI.
If you've researched how to get a jumbo loan with a low down payment and no mortgage insurance, you've probably seen lots of conflicting information.
Do you need 3% down or 30%? Do you need 6, 12, or 24 months of cash reserves? If you have a lower down payment, will you be required to have private mortgage insurance (PMI) or not?
The truth is that the answers to these questions will vary greatly depending on your lender.
In this post, we'll cover why there's a lot of misinformation surrounding jumbo loans and what you can do to improve your chances of qualifying for one with a low down payment and no private mortgage insurance (PMI).
Key Takeaways
- Jumbo loans are considered higher-risk loans for many lenders, so they often come with stricter requirements for borrowers.
- Some jumbo programs do not require mortgage insurance, even when the down payment is lower than 20%.
- Even though jumbo lending requirements vary, there are a few things you can do to strengthen your file, such as maximizing your credit score and shopping around for a flexible lender.
Why Do the Requirements for Jumbo Loans Vary?
Jumbo loans exceed the conforming loan limits set by the Federal Housing Finance Agency, which means they are not eligible for purchase by Fannie Mae or Freddie Mac when they are above those limits.
Since these loans are often considered riskier for lenders, many set their own stricter requirements for borrowers. Some lenders are more traditional with what they want borrowers to come to the table with, while others are more flexible.
Here's a quick chart that shows just how much these ranges can vary by lender and borrower profile:
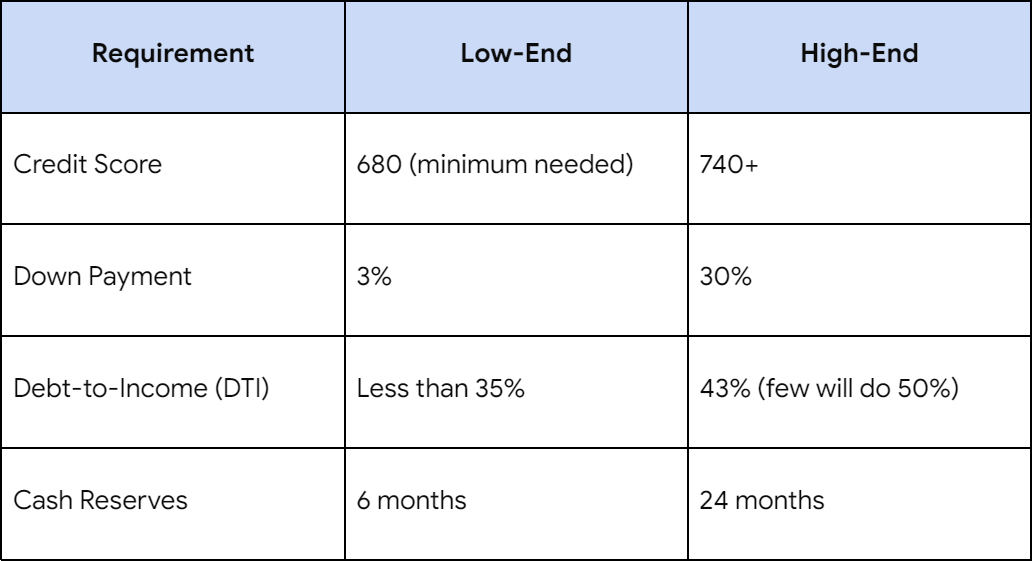
To better understand how these requirements influence each other, let's take a closer look at each factor.
Your Credit Score
Your credit score is one of the most important factors in determining whether you may qualify for a jumbo loan and what terms a lender may offer.
In general, stronger credit can help you qualify for a lower down payment, lower reserve requirements, or better pricing. Lower credit scores may lead to higher rates, larger required reserves, or a bigger down payment, depending on the lender.
It's important to ensure your credit score is as strong as it can be before applying for a jumbo loan.
Your Down Payment
The amount you'll need to put down depends on a few factors: your lender, credit score, loan amount, and overall financial profile.
Typically, the higher your credit score, the more likely you are to be considered for a lower down payment. However, some lenders may still require 20% down based on their own jumbo guidelines.
Loan amount matters too. As the loan size increases, lenders may require a larger down payment or additional reserves.
The best way to find out how much you'll need to put down is to talk to your lender.
Your Debt-to-Income Ratio
Aside from your credit score, this is another key factor lenders take into account when deciding whether to approve your jumbo loan.
Your DTI is a measure of how much debt you have compared to your total monthly income. Lenders use it to help assess whether you can comfortably manage your housing payment and other debts.
Many lenders prefer lower DTI ratios on jumbo loans, although acceptable limits can vary by lender and program. In general, a lower DTI can improve your chances of qualifying and may open up more options.
Your Cash Reserves
The amount of cash reserves required on top of the down payment can be a big shock for some people.
Many lenders want borrowers to have several months of reserves when applying for a jumbo loan, but the exact requirement varies. Some programs may be more flexible, while others may require substantially more reserves, especially for larger loan amounts or layered risk factors.
Remember, these loans are often viewed as riskier than conforming loans, so lenders want to see that borrowers have enough cash on hand to cover their monthly mortgage payments, especially if income unexpectedly decreases.
Do Jumbo Loans Require PMI?
Mortgage insurance protects the lender if a borrower defaults. On many conventional loans, private mortgage insurance is generally required when the down payment is less than 20%, according to the Consumer Financial Protection Bureau. But jumbo loans are not all structured the same way, and some lenders offer jumbo programs without monthly mortgage insurance.
Modern Day Lending offers jumbo options that may make it possible to qualify with no mortgage insurance, even if you have a lower down payment.
How Do You Get a Low Down Payment Jumbo Loan With No Mortgage Insurance?
To improve your chances of qualifying for a jumbo loan with a low down payment and no mortgage insurance, focus on a few key steps:
- Maximize your credit score: Minimum score requirements vary by lender and program, but stronger credit generally makes it easier to access better jumbo loan options.
- Prepare your down payment and cash reserves: Many jumbo lenders want to see both funds for the down payment and post-closing reserves. The more documented assets you have, the stronger your file may look.
- Look for a lender with flexible requirements: Many big banks tend to have stricter requirements for their jumbo loans, so it can help to shop around for a lender whose program fits your financial profile.
Jumbo Loans Without Jumbo Requirements
Many lenders want jumbo loan borrowers to have hefty down payments and large reserves, even if they advertise otherwise.
At Modern Day Lending, we know how daunting it can be to qualify for a jumbo loan, which is why we work to match borrowers with jumbo loan options that fit their financial situation.
If you're serious about qualifying for a jumbo loan but don't think you've got enough for your down payment, connect with a member of our team and see what options may be available to you.