What Is Loan-to-Value Ratio? Formula and Examples
Learn what loan-to-value, or LTV, means, how to calculate it, and how it can affect mortgage insurance, rates, refinancing, and loan options.
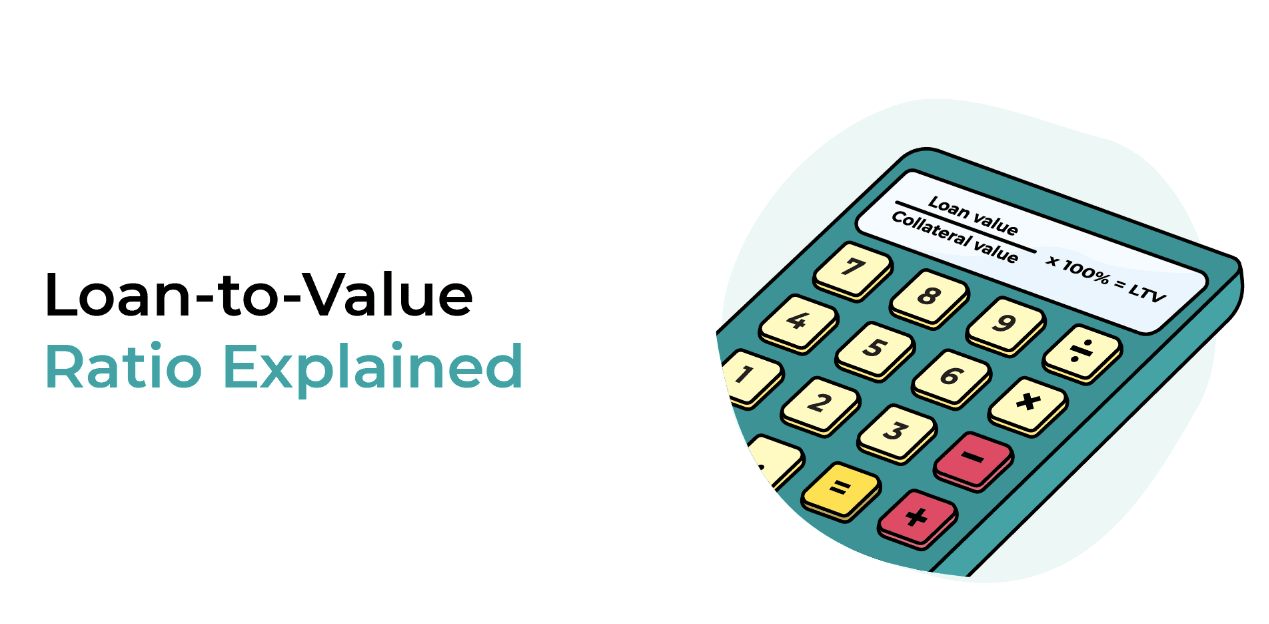
Loan-to-value ratio, or LTV, is the percentage of a home's value that you borrow. Lenders use it to measure risk when you buy, refinance, or borrow against home equity.
You calculate LTV by dividing the loan amount by the property's value, then multiplying by 100. For example, a $400,000 loan on a $500,000 home equals 80% LTV.
Your LTV matters because it can affect mortgage insurance, pricing, down payment requirements, and which loan programs may fit your scenario.
TLDR Key Takeaways
In a nutshell, a loan-to-value ratio is a financial measurement that compares your home's value versus the total amount of your loan.
The lower your LTV, the happier lenders are because it means you have more equity in the property.
For many conventional loans, private mortgage insurance is generally required when your LTV is above 80%, according to the Freddie Mac Seller/Servicer Guide.
What Is Loan-to-Value Ratio?
A loan-to-value ratio calculates the relationship between a loan amount and the appraised value of a property. In other words, it helps lenders determine whether or not the borrower has enough equity in the property to use as collateral to secure the loan.
It's just another way for mortgage lenders to ensure their investment is protected should the borrower run into financial difficulties during repayment.
Loan-to-value ratios come into play when buying a house, refinancing a current mortgage, or borrowing against a property's equity.
The higher the LTV, the riskier the loan is to the lender because if something happens to the borrower, the lender may need to resell the property to recoup its money. An unfavorable change in market prices can make this more difficult.
On the other hand, a lower LTV is viewed as less risky, which often results in better borrowing terms. But what exactly constitutes a low LTV? Generally speaking, LTVs of 80% or less are commonly viewed as lower risk.
Pro Tip: Down payments, sales prices, and appraised values all affect your overall LTV ratio. Higher down payments and lower sales prices result in a lower LTV ratio.
How LTV Affects Your Mortgage
While several factors like your credit score, income, and debt-to-income (DTI) ratio influence your eligibility for a mortgage, your LTV also plays a critical part in the lender's underwriting process.
As we mentioned before, most lenders tend to favor borrowers with a low LTV and may offer more competitive terms. That doesn't mean higher-LTV programs are unavailable, but they can come with more stringent requirements.
On top of having to jump through additional hoops, borrowers looking to secure a loan with a higher LTV will typically have:
Higher Interest Rates: Higher-LTV loans can be priced as riskier, so rates or fees may be higher depending on the program and borrower profile.
Private Mortgage Insurance (PMI): For many conventional loans, PMI is generally required when the LTV is above 80%, according to the Freddie Mac Seller/Servicer Guide. Some buyers use a piggyback loan to keep the first mortgage at 80% LTV and avoid PMI.
Limited Options: Borrowers may only have access to a smaller number of repayment options and terms.
Difficult Approval Process: Lenders will want to review your finances closely to evaluate your ability to repay the loan, and they may require additional documentation depending on the program.
If you want to get the best terms and rates available to you, you'll generally want to try to lower your LTV.
How to Calculate Your Loan-to-Value Ratio
To calculate your LTV, you'll need to divide the loan amount by the value of the property or asset. The formula below represents the equation:
LTV = (Mortgage Amount (MA) ÷ Appraised Property Value (APV)) x 100
For example, if you were looking to buy an investment property worth $500,000 and secured a loan for $400,000, your LTV would be 80%. Here's how that would look:
LTV (80%) = (MA ($400,000) ÷ APV ($500,000)) x 100
How Lenders Determine the Value in Your LTV Calculation
The "value" in your LTV calculation is not always the same in every transaction. On a purchase, lenders commonly compare the loan amount to the lower of the purchase price or appraised value. On a refinance, lenders typically use the current appraised value. That distinction matters because a low appraisal can raise your LTV even if your planned down payment does not change. For example, if you agree to pay $480,000 for a home that appraises at $500,000, a $384,000 loan is 80% LTV because the lender uses the $480,000 price.
What Is a Good LTV?
The lower your LTV ratio, the better. In practice, many loan programs treat 80% LTV as an important threshold because mortgage insurance rules and pricing often change above that level. With an 80% LTV or less, you may improve your chances of a successful application and may qualify for better pricing.
Quick Tips to Improve Your LTV Ratio
Making smart financial decisions is key to improving your LTV and gaining better access to more favorable mortgage options. Here are a few quick tips to help you improve it:
Maximize Your Down Payment
Your down payment directly influences your LTV. The more money you have to put down, the lower your LTV will be.
Try to set aside as much money as possible each month into savings so that you can increase the amount of money available to use as a down payment.
Wait for the Market to Change
We all know that the housing market fluctuates from year to year, even season to season. Paying attention to market trends can help you decide when the best time to start house hunting is.
If prices fall or inventory improves, you may be able to buy with a lower LTV and more favorable terms.
Pay Down Existing Debt
High levels of debt can make it harder to save for a down payment. Try to pay down or eliminate outstanding debt so you can free up money to apply to a down payment.
Make Extra Payments on Your Principal
If you're looking to refinance your home, you'll want to make sure you lower your LTV before reaching out to your lender. Remember, as you reduce your principal balance, your LTV ratio may decrease if your property value holds steady or rises. An extra payment toward principal can help reduce your balance faster.
Different Types of LTV Rules
When it comes to LTV ratio requirements, different loan types may have different rules.
FHA Loans
These mortgages, facilitated by FHA-approved lenders and insured by the Federal Housing Administration, can offer a lower down payment option for qualified borrowers.
FHA-insured purchase loans allow a maximum loan-to-value ratio of 96.5% for borrowers who meet FHA requirements, according to HUD.
FHA loans also require mortgage insurance. Whether it lasts for the life of the loan or for a shorter period depends on factors such as the original LTV and loan term, according to HUD's mortgage insurance guidance.
VA and USDA Loans
Eligible service members, veterans, and certain rural homebuyers may have access to VA and USDA loan programs.
These programs do not use conventional PMI, but they can include other upfront or annual fees depending on the program. For example, the VA funding fee and the USDA guarantee fee structure may apply.
Fannie Mae and Freddie Mac
Some conventional affordable lending programs support down payments as low as 3%, which can result in 97% LTV financing for qualified borrowers. See Fannie Mae HomeReady and Freddie Mac Home Possible.
For many conventional loans sold to Fannie Mae or Freddie Mac, mortgage insurance may be canceled once borrower-request and automatic termination rules are met under the CFPB's summary of the Homeowners Protection Act.
Refinance options and high-LTV relief programs change over time, so borrowers considering a refinance should confirm current availability and eligibility with their lender and the relevant agency or GSE guidance.
What's the Difference Between LTV and Combined LTV (CLTV)?
LTV and CLTV are tools for assessing the financial implications of mortgages on a property. LTV measures the impact of a single mortgage loan on a property, while CLTV takes into account all loans that are secured by that same property, including:
Primary mortgage
Second mortgage(s)
Home equity loan(s)
Lines of credit
Other liens
By measuring individual loan values, as well as all outstanding loans secured by the property, these ratios can help lenders evaluate risk when a borrower has more than one loan.
For example, if they have multiple mortgages and a home equity loan or line of credit (HELOC), the CLTV may indicate too much risk.
While 80% and above is a common CLTV benchmark, some lenders may be more flexible, although they will most likely have stronger qualifying standards for borrowers to meet.
Why LTV Matters Before You Apply
Your loan-to-value ratio affects more than your down payment. It can influence mortgage insurance, pricing, refinance options, and how much flexibility you have across loan programs.
If you are comparing scenarios, focus on three variables first: your loan amount, the property's value, and whether the transaction is a purchase or refinance. Small changes in any of those can move your LTV enough to affect your options.
If you want help reviewing your LTV and the loan programs that may fit it, schedule a consultation with Modern Day Lending.
Frequently Asked Questions
What is loan-to-value ratio in a mortgage?
Loan-to-value ratio, or LTV, is the percentage of a home's value that is financed with a mortgage. Lenders use it to evaluate risk. A lower LTV usually means more borrower equity, while a higher LTV can lead to tighter guidelines, mortgage insurance, or different pricing.
How do you calculate loan-to-value ratio?
To calculate LTV, divide the loan amount by the property's value and multiply by 100. If you borrow $400,000 on a $500,000 home, the calculation is $400,000 divided by $500,000, which equals 0.80, or 80% LTV.
What is considered a good LTV ratio?
In many mortgage scenarios, 80% LTV or lower is an important benchmark because mortgage insurance rules and pricing often change above that level. Still, the right LTV depends on the loan program, occupancy, property type, credit profile, and whether you are buying or refinancing.
Does LTV affect PMI?
Yes. For many conventional loans, private mortgage insurance is generally required when the LTV is above 80%. Government-backed loans may use different mortgage insurance or fee structures, so the impact depends on the program you choose.
What is the difference between LTV and CLTV?
LTV looks at one primary mortgage compared with the property's value. CLTV, or combined loan-to-value ratio, includes all loans secured by the property, such as a first mortgage, second mortgage, HELOC, or home equity loan. Lenders use CLTV when more than one lien is involved.
What does a 70% LTV mean?
A 70% LTV means you are borrowing 70% of the home's value and covering the other 30% with your down payment or existing equity. For example, a $350,000 loan on a $500,000 home is 70% LTV.